

Rating: Cautiously Bullish| Target Price: $40.00 | Current Price: $19.13 | Implied Change: +109.1%
AUTHOR’S TAKE
MoonLake Immunotherapeutics is a fascinating but highly polarizing story in the small-cap biotech space, where an incredibly potent drug is clashing with intense clinical and financial risks. On one hand, you have a next-generation molecule showing top-tier long-term data in patients. On the other hand, the company is walking a tightrope due to a rocky clinical history and a tight cash runway. The absolute make-or-break milestone for this stock is the upcoming Biologics License Application filing with the US FDA, scheduled for late September 2026. This submission is aiming for approval in moderate-to-severe hidradenitis suppurativa, but it faces a steep hurdle because the drug actually failed one of its twin Phase 3 studies at the 16-week mark. While the market remains completely divided on whether regulators will look past that hiccup, MoonLake’s unencumbered global rights and its cash position help establish a solid technical valuation floor at $14.50 per share.
STRATEGY AND PIPELINE
Based out of Zug, Switzerland, MoonLake Immunotherapeutics is a late-stage biopharmaceutical firm operating with a very straightforward, high-stakes business model. They are entirely an undiversified, single-asset company. If you buy MoonLake, you are placing a singular bet on sonelokimab. This asset is an 85 kilodalton tri-specific single-domain VHH antibody fragment, which is just a technical way of saying it is an engineered Nanobody. Unlike the massive, clunky conventional antibodies used in older drugs, sonelokimab is about 1/10 the size because it lacks the traditional structural tail. Licensed from Ablynx and Merck KGaA, this tiny size is the drug’s ultimate weapon. It is built to dive deep into thick, poorly vascularized, and highly inflamed tissues that larger molecules struggle to penetrate, such as the painful deep dermal tunnels that form under the skin in hidradenitis suppurativa or the stiff, inflamed joints of arthritic patients.
Because they are still in the clinic, MoonLake generates no revenue today. Their game plan is to launch sonelokimab independently in big-ticket regions like the United States and Europe while looking for regional partners elsewhere. To maximize the value of their lone asset, management has branched sonelokimab into 3 parallel late-stage clinical programs. You have the Phase 3 VELA trials for adults with hidradenitis suppurativa, the Phase 3 IZAR program for adult psoriatic arthritis, and the Phase 3 VELA-TEEN study targeting adolescents. Hidradenitis suppurativa alone represents a $10 billion global market opportunity. It is a terrible disease with a huge unmet need, as the current standard therapies often fail to offer patients deep or lasting relief, which leaves the door wide open for a highly penetrative drug to step in and capture the market.
CLINICAL PERFORMANCE AND METHODOLOGY
When you look purely at the long-term data, sonelokimab looks like an absolute powerhouse. In the full 52-week pooled data from the Phase 3 VELA trials, an impressive 67.2% of patients on the optimized dose achieved a 75% reduction in symptoms, a metric known as HiSCR75. Even better, higher hurdles like HiSCR90 and total skin clearance showed a steady, upward climb over time, proving the drug keeps working the longer patients stay on it. Over in the rheumatology space, the Phase 2 ARGO trial for psoriatic arthritis showed that the drug separated itself from the placebo arm in as little as two weeks, with both the 60 milligram and 120 milligram doses putting up excellent ACR50 and ACR70 response rates by Week 24.
However, the road here has been incredibly bumpy. The stock took a massive hit in late 2025 because management decided to split the adult VELA program into two identical twin trials, called VELA-1 and VELA-2. While one of those trials was a clear win, the drug unexpectedly missed statistical significance on its primary endpoint in the other twin trial at Week 16. This split execution triggered chaos in the market, highlighting how unpredictable global clinical trials can be when patient populations differ across regions. On the safety front, the drug behaves well, but blocking both IL-17A and IL-17F comes with a known trade-off: it weakens the body’s local defenses against fungal infections, which caused mild-to-moderate oral thrush in 2-3% of patients in the ARGO trial. Investors are keeping a close eye on the ongoing open-label extensions to make sure these issues, alongside potential anti-drug antibodies, don’t limit the drug’s real-world usability.
MOAT, IP, REGULATION, AND STRUCTURAL ADVANTAGES
MoonLake’s defensive moat is built on robust patents, specialized biological regulatory protections, and a manufacturing process that is incredibly tough to copy. Their core composition-of-matter and formulation patents are solid, keeping cheap copycats away until the late 2030s and early 2040s. If the FDA gives them the green light, sonelokimab will also enjoy 12 years of regulatory data exclusivity in the US as an innovative biologic, alongside 10 years of market protection in Europe.
Beyond the legal paperwork, the drug has a massive structural advantage because of its physical design. Making tri-specific single-domain Nanobodies at a commercial scale is an entirely different beast than making regular antibodies. It requires highly specific yeast and microbial expression systems, and because MoonLake out-sources this work to third-party Contract Manufacturing Organizations, it creates a steep technical barrier to entry. Any generic or biosimilar competitor trying to replicate this process faces massive up-front costs and years of technical optimization, giving MoonLake substantial long-term pricing power.
THE BULL CASE
The bull case is the FDA looks at the big picture, accepts the long-term 52-week durability data, and forgives the early Week 16 miss in the second twin trial. The big catalysts to watch are a smooth BLA filing this September and positive Phase 3 readouts from the IZAR trials in early 2027. Right now, Wall Street is likely mispricing this stock because it is overly focused on the historical trial split and recent share dilution. If sonelokimab gets approved with a clean label, its best-in-class efficacy data will allow it to quickly win over dermatologists. By capturing just 15% of the moderate-to-severe hidradenitis suppurativa market, the drug can easily scale past $2 billion in peak sales, driving a major corporate re-rating and pushing the stock up into the $40-$45 range.
THE BEAR CASE
The bear case is the glaring vulnerability of being a single-asset company. Because regulators almost always demand 2 clean, independently successful trials for approval, sonelokimab’s mixed Phase 3 results put it in a very dangerous position. If the FDA hands MoonLake a Refusal to File letter or demands a brand-new, multi-year trial during their review late this year, the stock will collapse. There is also a risk that dual IL-17 inhibition leads to harsher safety labels or higher rates of oral thrush, which would hurt adoption. Moreover, if MoonLake has to go it alone without a big pharma partner, they will have to build a commercial sales force from scratch in a market heavily dominated by entrenched blockbusters. If the launch stalls and cash runs dry, massive, dilutive share printing will be inevitable, cratering the stock down to a painful $5-$7.
FINANCIAL POSITION, UNIT ECONOMICS, AND RUNWAY
MoonLake is burning through cash quickly to fund its late-stage trials, which is typical for a pre-revenue biotech firm. To shore up the balance sheet, management pulled off an upsized public offering in late June 2026, selling 9 million ordinary shares at $20 apiece, along with 1 million pre-funded warrants. This move brought in $200 million in gross cash, pushing their total liquidity up to roughly $420 million against 0 long-term debt. Looking at their recent Q1 2026 numbers, the company posted a net loss of $69.7 million, a miss driven by the costs of running parallel global Phase 3 trials.
Over the next year, the company’s quarterly burn rate is expected to hover around $55 million as active trial sites wind down and move patients into long-term extensions. While the recent cash injection helps, their runway is structurally tight and only stretches into late 2027 or early 2028. This timeline creates an operational trap because their cash will be running low at the exact same time the FDA is reviewing the BLA. Unless they secure a lucrative partnership with a larger pharmaceutical company, MoonLake will be forced to raise more capital through dilutive equity rounds or expensive debt right before the commercial launch.
MARKET AND COMPETITION
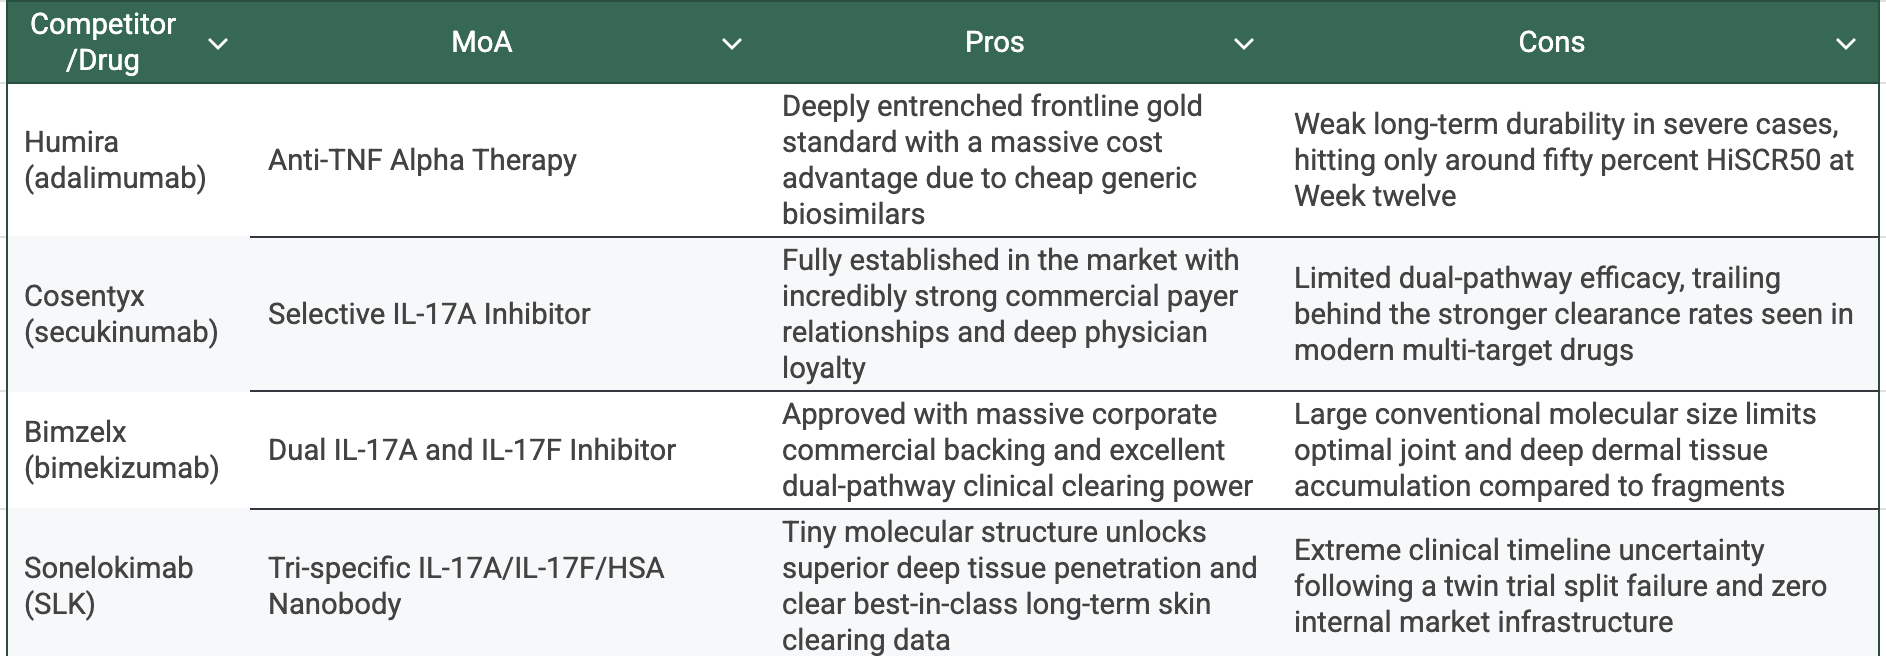
The market for advanced systemic inflammatory drugs is a brutal, crowded space dominated by massive pharmaceutical companies with endless commercial resources. On top of that, pharmacy benefit managers act as strict gatekeepers, enforcing tough prior authorization rules that force patients to try and fail cheap, generic anti-TNF therapies before they can ever get access to a premium biological drug like sonelokimab.
KEY CATALYSTS AND TIMELINE
Phase 3 VELA adult hidradenitis suppurativa long-term extension data: July 2026
Biologics License Application submission to the US FDA for sonelokimab in HS: September 2026
Phase 3 VELA-TEEN top-line clinical trial readout in adolescent HS: November 2026
Phase 3 IZAR-1 and IZAR-2 top-line data readouts in psoriatic arthritis: Q1 2027
US FDA regulatory approval decision and commercial launch milestone: Q3 2027
VALUATION
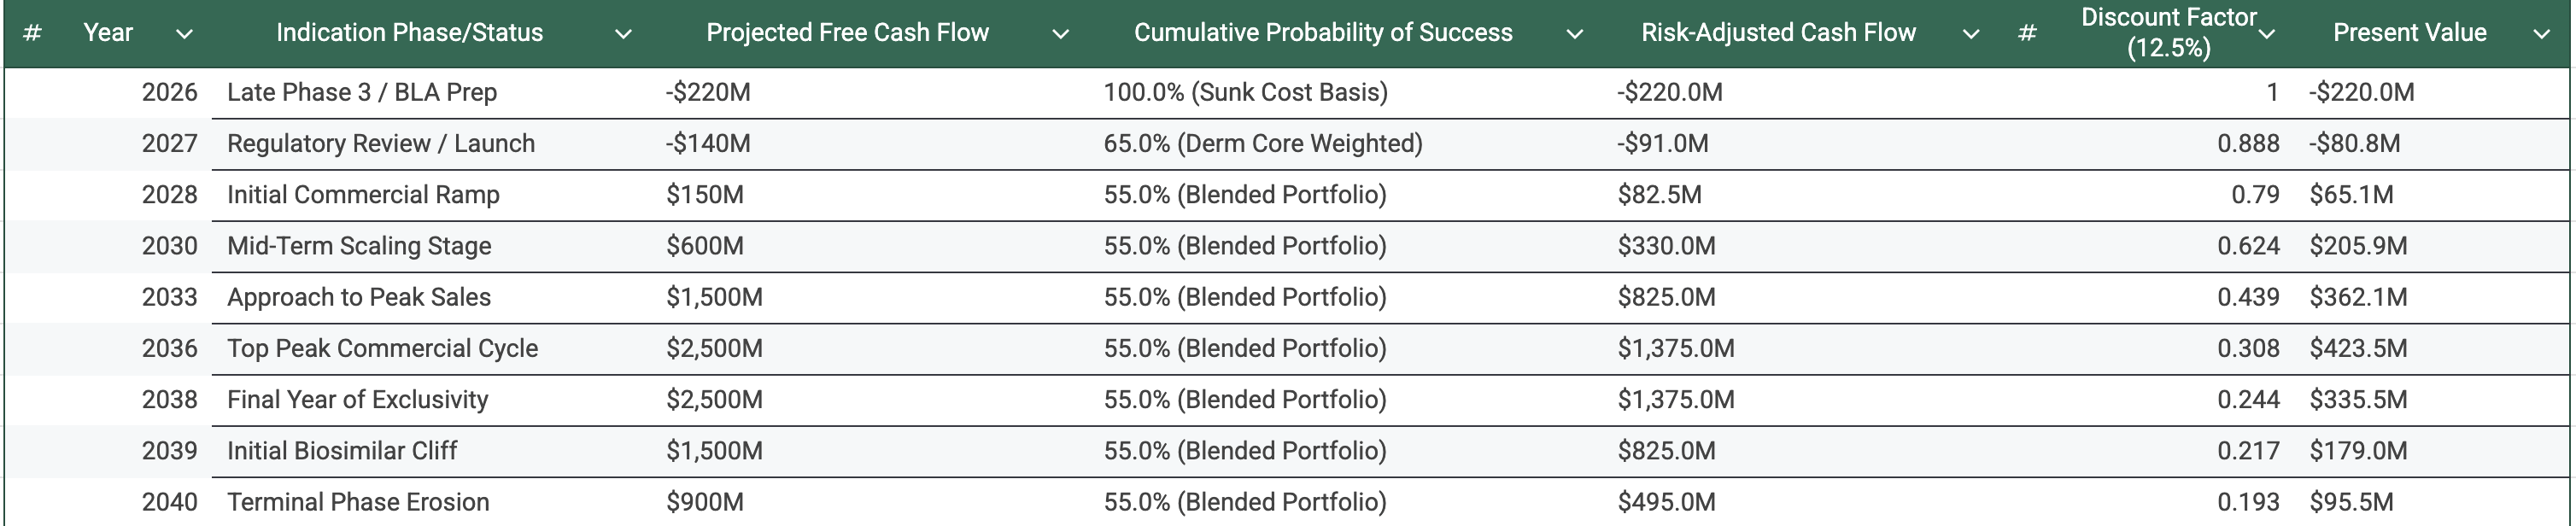
The $40 target price comes from a risk-adjusted Net Present Value model that tracks sonelokimab’s potential cash flows through 2040, assuming the drug’s revenue drops to 0 as soon as its patents expire.
rNPV Valuation Assumptions Category: Probability of Success
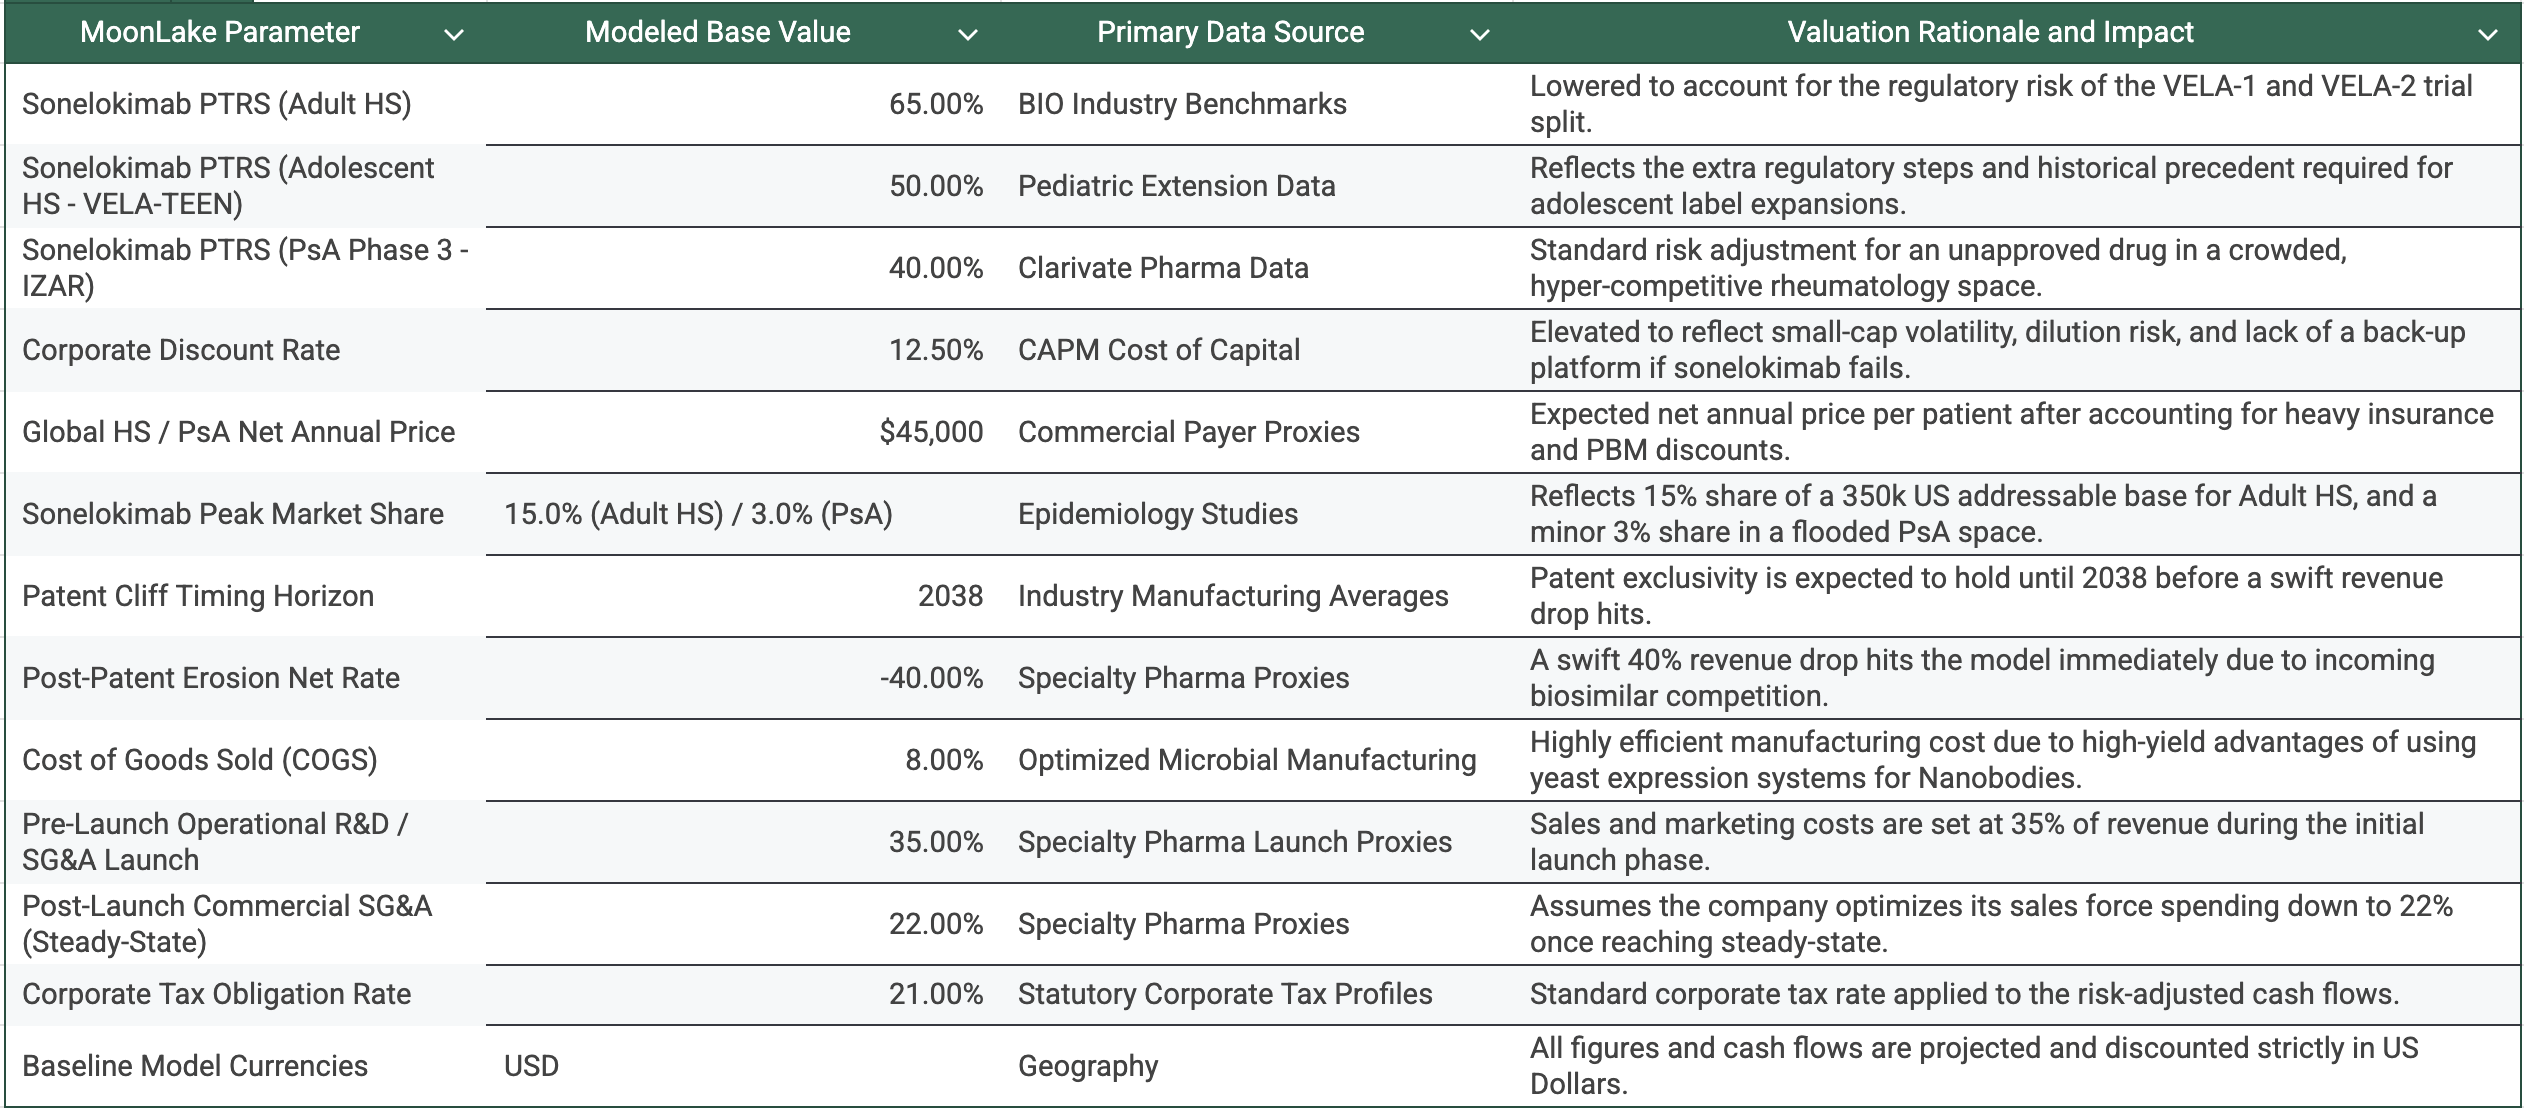
The Probability of Technical and Regulatory Success for the hidradenitis suppurativa indication is modeled at 65%. While a successful Phase 3 drug usually gets an 85% probability rating, a lower number is used here to account for the regulatory risk caused by the VELA-1 and VELA-2 trial split. For the psoriatic arthritis track, the Probability of Success is set at 40%, which fits standard industry benchmarks for late-stage rheumatology assets that still need to prove themselves in ongoing Phase 3 trials within a hyper-competitive market.
rNPV Valuation Assumptions Category: Peak Sales and Market Share
Peak sales for hidradenitis suppurativa are modeled at $1.2 billion in the US and $500 million in Europe, reaching peak market penetration 9 years after the drug launches. This assumes an addressable base of 350k moderate-to-severe patients in the US, a conservative 15% peak market share, and a net annual price of $45k per patient. For psoriatic arthritis, peak global sales are modeled at a modest $800 million, assuming a tiny 3% market share because the space is already flooded with blockbuster drugs.
rNPV Valuation Assumptions Category: Financial Metrics and Discount Rate
A discount rate of 12.5% includes an elevated risk premium to reflect the volatility of small-cap biotech stocks, the dilution risk, and the fact that MoonLake has no back-up assets if sonelokimab fails. Cost of Goods Sold is modeled at a highly efficient 8% of revenue due to optimized microbial manufacturing. Sales and marketing costs are set at 35% of revenue during the initial launch phase before dropping to 22% at steady-state, while G&A costs are fixed at $45 million a year. A 21% corporate tax rate is applied, and patent exclusivity is expected to hold until 2038 before a swift 40% revenue drop hits due to biosimilar competition.
The table below breaks down the risk-adjusted cash flows, cumulative probabilities, and present value discounting steps used over the core asset commercialization timeline.
Sensitivity Analysis
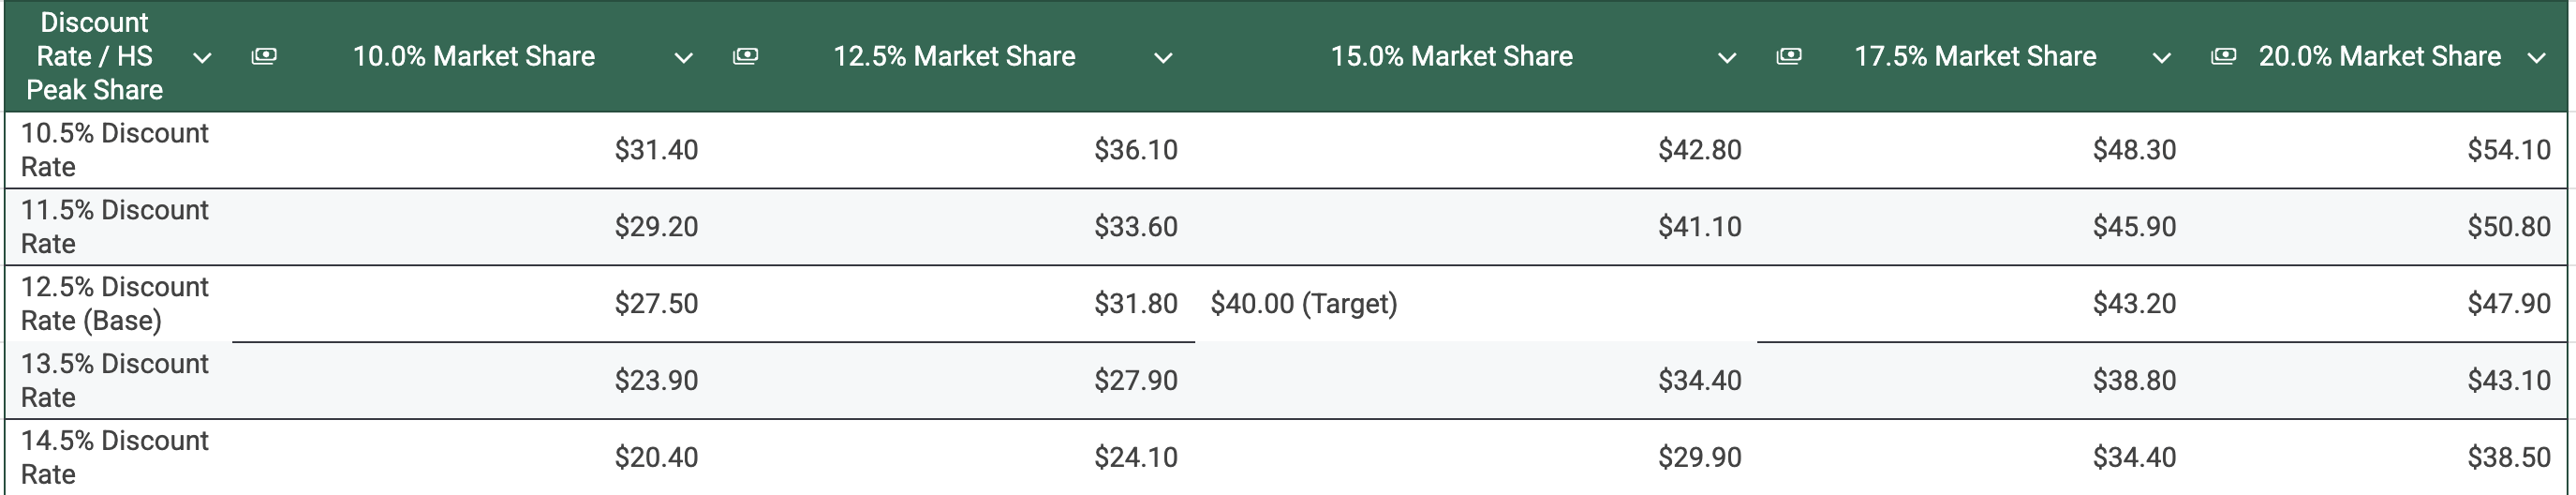
The table below shows how sensitive the target price is to shifts in the cost of capital discount rate and the final peak market share achieved in the primary hidradenitis suppurativa market.
Assumptions Summary Table
Disclosure
This Due Diligence report is for informational purposes only and does not constitute financial advice or a recommendation to buy, sell, or hold any securities. The information is based on public filings and media reports and may not be exhaustive or entirely accurate. Investing in biotechnology companies, especially those in clinical stages of development, involves inherent risks, including the complete loss of capital. Clinical trial outcomes, regulatory pathways, and eventual commercial success are subject to uncertainty. Readers should conduct their own thorough due diligence and consult with a qualified financial advisor before making any investment decisions. The author may hold long positions in Moonlake Therapeutics ($MLTX) and has received no compensation for this report.