

Rating: BULLISH | Target Price: $54.00 | Current Price: $33.93 | Implied Change: +59.1%
Author’s Take
Edgewise Therapeutics is sitting on a massive pile of cash that completely changes the financial realities for this stock. By selling its muscular dystrophy pipeline to Servier for up to $2.65 billion, Edgewise secured $1.55 billion in upfront cash. That alone gives the stock an absolute floor of about $25.00 per share in net cash, meaning there is minimal structural downside from current trading levels. Right now, the market is completely overlooking the value of its remaining heart drug, EDG-7500. The big clinical inflection point to watch is the upcoming 12-week Phase 2 data readout for EDG-7500 in hypertrophic cardiomyopathy, which is scheduled for the second quarter of 2026. If that data looks good, it sets a direct path for Phase 3 trials in the second half of 2026. This deal allows Edgewise to let Servier handle the expensive, long-term muscular dystrophy trials while keeping over a billion dollars in potential milestone payouts, leaving Edgewise with a pure-play capital structure to focus entirely on the massive heart disease market.
STRATEGY AND PIPELINE
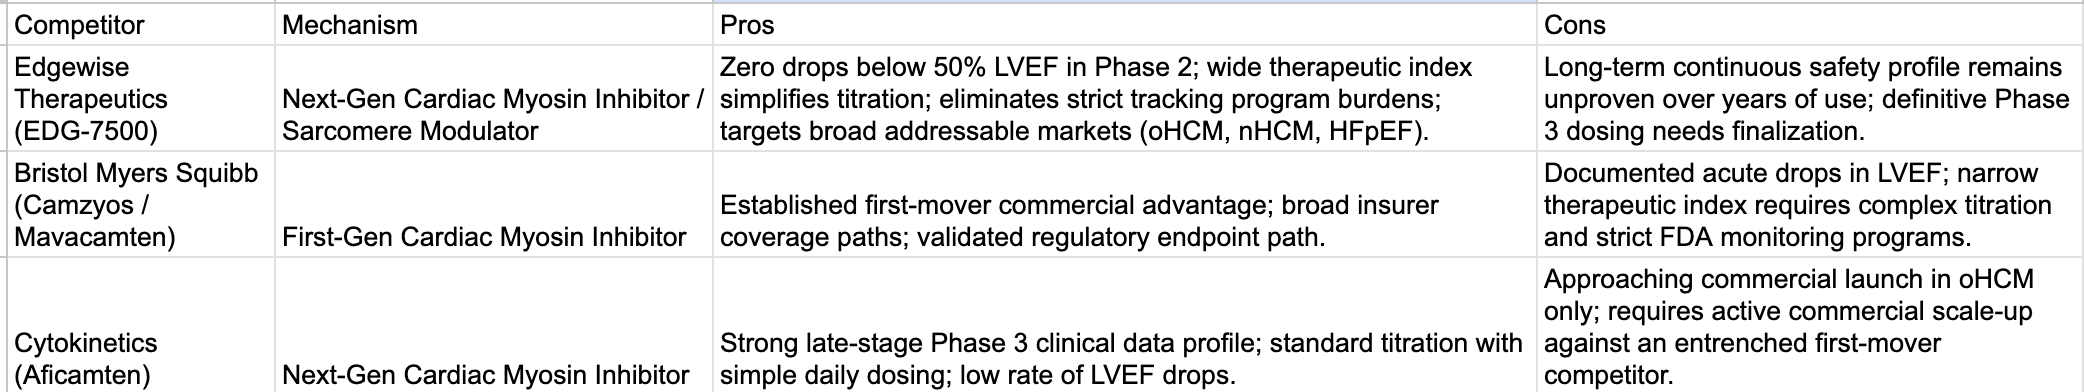
Edgewise Therapeutics focuses on discovering small molecule drugs that fine-tune how muscles contract. After selling its neuromuscular programs, the company is now fully dedicated to treating serious heart conditions. Rather than acting as a blunt force mechanical inhibitor across the entire contractile cycle, EDG-7500 acts as a highly selective cardiac sarcomere modulator that targets cardiac myosin to slow down excessive heart muscle contractions. This helps lower left ventricular outflow tract gradients and allows the heart to relax properly without reducing the left ventricular ejection fraction to dangerous levels. The business model has shifted from standard clinical development to a mix of asset monetization and targeted internal research. Selling sevasemten to Servier wiped out all of Edgewise’s neuromuscular development expenses while keeping the company eligible for $1.1 billion in future milestone payments. Now, the internal pipeline is led by EDG-7500 for both obstructive and nonobstructive hypertrophic cardiomyopathy, followed by EDG-15400 for heart failure with preserved ejection fraction. These heart assets target multi-billion dollar markets that are currently underserved by older treatments.
CLINICAL PERFORMANCE AND METHODOLOGY
The scientific foundation for Edgewise depends on data from the ongoing Phase 2 CIRRUS-HCM trial and earlier Phase 1 studies in healthy volunteers. The trial is designed with multiple groups of patients taking different doses to evaluate safety, drug behavior in the body, and overall effectiveness. In the earlier Phase 2 cohorts of patients with obstructive hypertrophic cardiomyopathy, EDG-7500 significantly lowered heart gradients based on the dose given. Most importantly, the drug achieved this reduction without causing a single patient’s ejection fraction to drop below 50%, which has been a major safety issue for older drugs in this class. Tests also showed positive trends in heart stress biomarkers like NT-proBNP. The current Part D portion of the trial is testing patients over 12 weeks to see how well EDG-7500 maintains gradient control and improves daily physical function. We still need to see how the safety profile holds up over years of continuous use, and the company must finalize the exact doses for Phase 3. Meanwhile, the clinical responsibilities for the older muscular dystrophy drug have completely shifted to Servier, leaving Edgewise to focus purely on heart data.
MOAT, IP, REGULATION, AND STRUCTURAL ADVANTAGES
Edgewise has built strong defenses around its business through patents, drug design, and a unique cash position. The company holds composition-of-matter patents for EDG-7500 that protect its molecular design well into the late 2030s and early 2040s. Competitors cannot easily copy this approach because EDG-7500 interacts with heart tissue in a highly specific way, creating a wider safety window than first-generation drugs. Because it does not cause the sudden drops in heart pumping strength seen with older treatments, Edgewise might avoid the strict FDA safety tracking programs that restrict competitor sales. On top of that, the cash from the Servier deal gives Edgewise a major financial advantage. The company does not need to issue new shares or take on expensive debt, allowing it to fund its Phase 2 heart failure trials and develop EDG-15400 without running out of money.
THE BULL CASE
The positive scenario relies on strong 12-week data from the CIRRUS-HCM trial in the second quarter of 2026. If the data shows excellent gradient reduction and zero dangerous drops in heart function, EDG-7500 will look like a superior option to current drugs on the market like Camzyos. Once the Servier deal closes in the third quarter of 2026 and the Phase 3 trial design is finalized, the stock should rise significantly as investors realize the company is backed by billions in cash and a highly promising heart drug. Moving EDG-7500 into broader Phase 2 trials for heart failure with preserved ejection fraction would open up another massive market. If Edgewise captures 25% of the global market for hypertrophic cardiomyopathy, the stock could reasonably trade between $54.00 and $65.00 by the end of 2026.
THE BEAR CASE
The negative scenario comes down to the typical risks of clinical drug development. If the 12-week data reveals hidden side effects or shows patient heart function dropping below the safe 50% threshold, EDG-7500 will lose its competitive edge and face strict FDA warnings. Additionally, if the Servier deal faces unexpected regulatory delays past the third quarter of 2026, Edgewise will have to burn through its current cash faster than expected. The company also faces heavy competition if rivals launch generic versions or better versions of their own drugs earlier than forecasted. If the heart pipeline fails, the company would have no other advanced assets to fall back on, causing the stock to drop to its baseline liquidation value of $20.00 to $22.00 per share.
FINANCIAL POSITION, UNIT ECONOMICS, AND RUNWAY
Edgewise is in a remarkably strong financial position due to its recent asset sale. In the first quarter of 2026, the company posted a net loss of $49.0 million, spending $42.7 million on research and $11.5 million on administration. While that spending level was high, the closing of the Servier deal changes everything by bringing in $1.55 billion upfront. This deal also hands over all the expensive muscular dystrophy trials to Servier, significantly cutting down Edgewise’s quarterly spending. With its primary focus now narrowed to the heart pipeline, the company’s total available cash will jump over $1.8 billion. This gives Edgewise a funding runway of more than seven years, removing the risk of diluting current shareholders before the Phase 3 trials are finished.
MARKET AND COMPETITION
KEY CATALYSTS AND TIMELINE
Q2 2026: Top-line 12-week data from the Phase 2 CIRRUS-HCM trial in patients with obstructive and nonobstructive hypertrophic cardiomyopathy.
Q3 2026: Expected closing and regulatory approval of the $2.65 billion muscular dystrophy asset sale to Servier.
H2 2026: Start of the pivotal Phase 3 trial for EDG-7500 in obstructive hypertrophic cardiomyopathy.
H2 2026: Start of the Phase 2 trial for EDG-7500 in patients with heart failure with preserved ejection fraction.
Q4 2026: Expected Phase 2 data from the GRAND CANYON trial for sevasemten, which is now funded by Servier but eligible for Edgewise milestones.
VALUATION
The $54.00 target price is based on a sum-of-the-parts risk-adjusted net present value model for the heart assets, combined with the cash value generated by the Servier transaction.
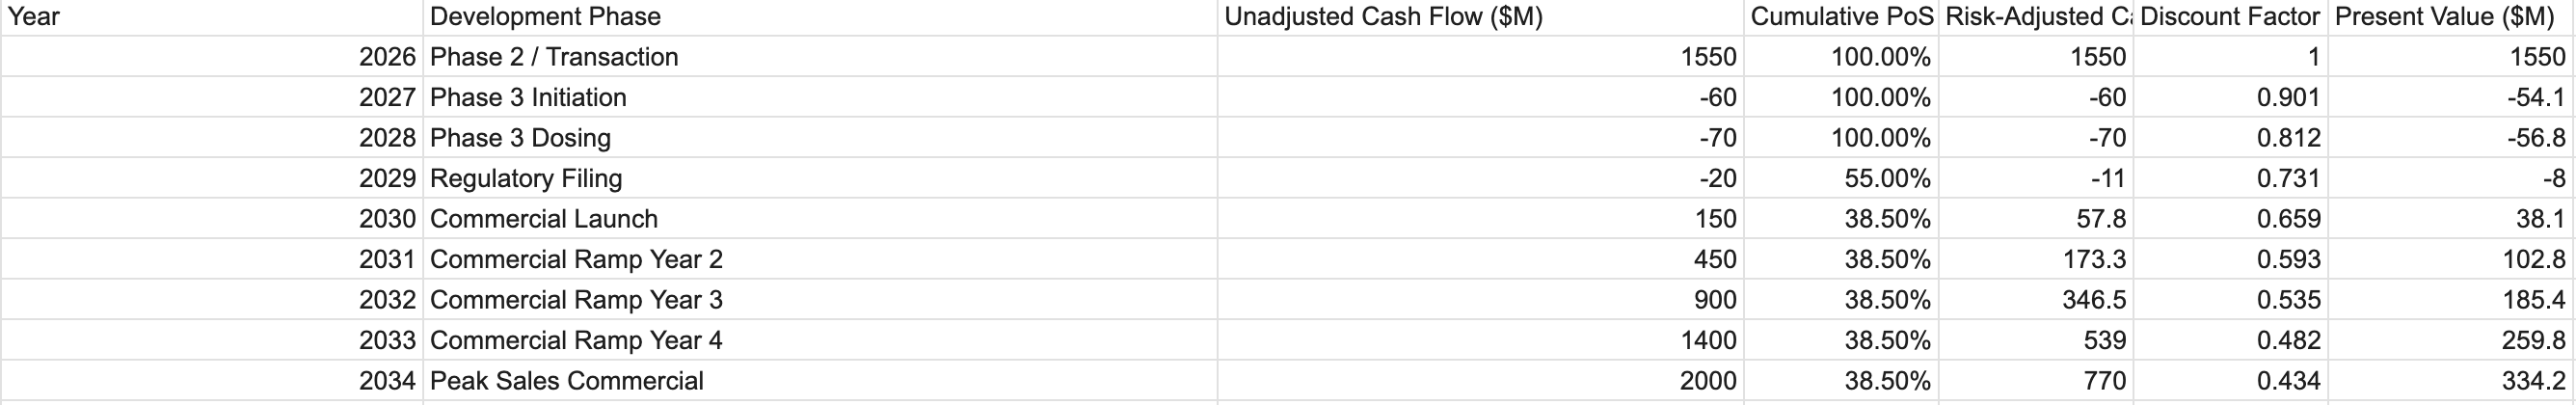
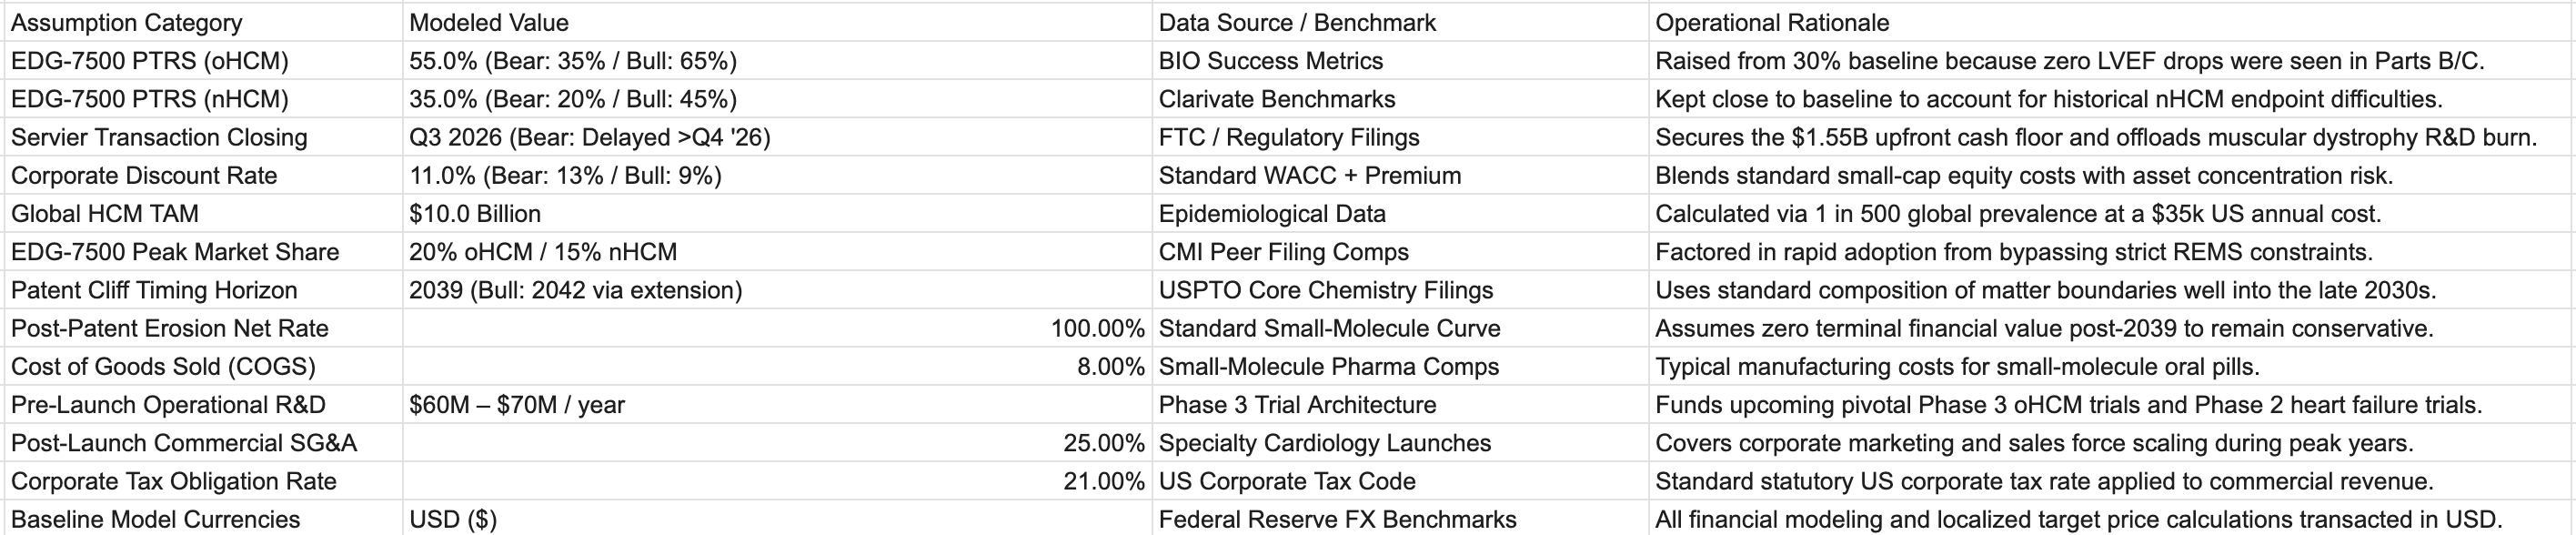
Probability of Success (PoS) Assumptions The probability of moving from Phase 2 to Phase 3 for EDG-7500 in obstructive hypertrophic cardiomyopathy is set at 55%. This is higher than the standard 30% industry baseline. The higher probability is justified by the positive early data from the CIRRUS-HCM trial, which showed consistent gradient reduction without safety failures. The probability of moving from Phase 3 to final regulatory approval is set at 70%, matching industry averages for heart drugs with clear physical endpoints. For the nonobstructive hypertrophic cardiomyopathy indication, the Phase 2 to Phase 3 success rate is lowered to 35% due to the historic difficulty of tracking nonobstructive disease symptoms. The milestone payments from Servier for the muscular dystrophy drug are given a 75% probability of success for near-term approvals, based on long-term data presented at recent medical conferences.
Market Size and Commercialization Assumptions
The total addressable market for hypertrophic cardiomyopathy is estimated at $10.0 billion globally. This comes from a diagnosed rate of roughly 1 in 500 people and an expected drug price of $35,000 per year for each patient. EDG-7500 is projected to capture a 20% share of the obstructive market and a 15% share of the nonobstructive market, assuming its safety profile helps patients avoid the complicated monitoring required by older drugs. The model assumes it will take 6 years after launch to reach peak sales, with a standard multi-year launch path where the drug takes 5 years to hit half of its peak market potential. Manufacturing costs are estimated at 8% of revenue, which is typical for small molecule pills. Operating expenses for marketing, sales forces, and additional trials are set at 25% of annual revenue during peak years. The corporate tax rate is set at 21%, and all calculations use US dollars. Patent protection runs through 2039 based on current filings, and the model assumes zero financial value after that patent cliff to remain conservative.
Discount Rate and Calculation Logic
An 11% discount rate is applied to all future cash flows. This represents the typical cost of capital for a mid-stage biotech company, combining a 4% risk-free rate with an extra premium to account for the risk of focusing heavily on a single drug platform. The math multiplies each year’s unadjusted cash flow by the cumulative success probability and discounts it back using the 11% rate.
rNPV Cash Flow Breakdown Table
Evaluation and Sensitivity Analysis
To keep the model conservative, the early-stage EDG-15400 heart failure asset is valued at zero because it does not have human data yet. The target price is highly sensitive to changes in the institutional discount rate and the final Phase 2 success probability for EDG-7500.
Valuation Sensitivity Matrix
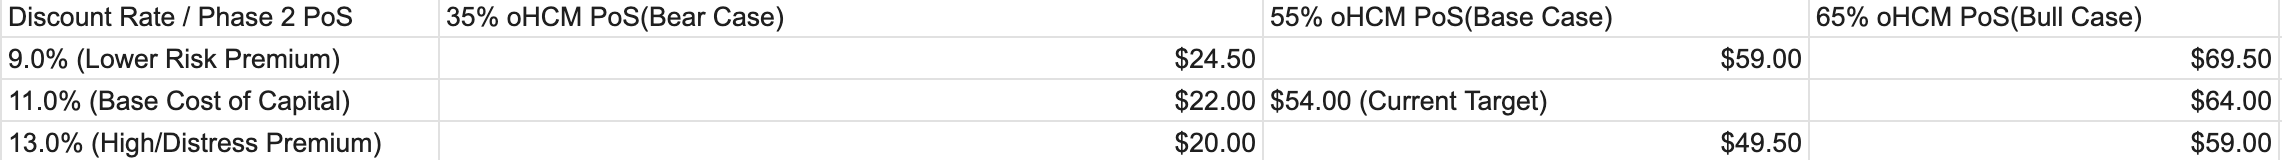
Assumptions Summary
Disclosure
This Due Diligence report is for informational purposes only and does not constitute financial advice or a recommendation to buy, sell, or hold any securities. The information is based on public filings and media reports and may not be exhaustive or entirely accurate. Investing in biotechnology companies, especially those in clinical stages of development, involves inherent risks, including the complete loss of capital. Clinical trial outcomes, regulatory pathways, and eventual commercial success are subject to uncertainty. Readers should conduct their own thorough due diligence and consult with a qualified financial advisor before making any investment decisions. The author may hold long positions in Edgewise Therapeutics ($EWTX) and has received no compensation for this report.