

Rating: BULLISH | Target Price: $8.50 | Current Price: $3.64 | Implied Upside: +134%
AUTHOR’S TAKE
I think the market has completely misread MannKind. Wall Street still treats it like a left-for-dead diabetes company with one product, missing the fact that it has turned into a diversified rare disease business. My core thesis rests on a gap between perception and reality: investors are completely ignoring the massive cash coming in from Tyvaso DPI royalties and the smart, recent addition of scPharmaceuticals. We are sitting on huge milestones right now, with an FDA decision on their pediatric insulin coming up immediately, followed by a decision on their new Furoscix injector device. Because their partner royalties provide a hard cash floor at $2.20 per share, you are getting a highly protected downside along with a completely free shot at their internal pipeline.
STRATEGY AND PIPELINE
MannKind’s whole strategy relies on taking massive drugs that have awful side effects or require rough injections and reformulating them into a dry powder you simply inhale. They do this with their own technology called Technosphere, which gets the medicine directly into the deep lungs and into the bloodstream almost instantly. They pull in cash from three places: direct sales of their inhaled insulin Afrezza, sales of their newly acquired heart failure drug Furoscix, and high-margin manufacturing fees and royalties from Tyvaso DPI, which United Therapeutics sells. Management has spent the last few years intentionally moving away from the expensive, crowded adult diabetes space to focus on rare lung and heart conditions. Buying scPharmaceuticals was a great strategic move because it immediately diversified their revenue. Their most important experimental drug is Nintedanib DPI for idiopathic pulmonary fibrosis. This matters because the current standard pill causes such terrible stomach issues that a third of patients simply quit taking it; MannKind’s version goes straight to the lungs to bypass the gut entirely. They are also working on an inhaled version of Ralinepag and Bumetanide using this exact same approach.
CLINICAL PERFORMANCE AND METHODOLOGY
The clinical data behind their products is exceptionally solid. For Afrezza, their pediatric trial called INHALE-1 compared inhaled insulin to daily shots in kids with type 1 diabetes. The numbers showed that their optimized dosing cut mealtime blood sugar spikes by 58% compared to injections, hitting their efficacy targets with fewer dangerous blood sugar drops and zero lung issues for the kids. For Furoscix, the clinical trials proved that an 80 mg under-the-skin injection matched the exact bioavailability and fluid-clearing power of a standard hospital IV. This lets heart failure patients treat severe fluid build-up at home instead of taking up a hospital bed. They are upgrading this device with the Furoscix ReadyFlow Autoinjector to deliver that same dose in under 10 seconds, and the bioequivalence data is currently sitting with the FDA. In their lung pipeline, early data from the Phase 1b study of Nintedanib DPI showed perfect tolerability, with zero patients dropping out or suffering from the stomach issues caused by the pill version. They are now moving into a Phase 2 trial to prove local lung engagement and show it slows down the loss of lung capacity. The main unknown left to solve is how the lung tissue handles long-term, daily inhalation of these specific compounds over a period of years, which is what these trials are designed to track.
MOAT, IP, REGULATION, AND STRUCTURAL ADVANTAGES
MannKind has built a very real competitive advantage that is incredibly hard to copy. Their core moat is the Technosphere platform, protected by a global web of patents on the particle chemistry, inhaler designs, and manufacturing processes that run out to the late 2030s. Beyond the legal patents, actually making these tiny, uniform powder particles requires specialized, expensive machinery that MannKind built and operates out of their own plant in Danbury, Connecticut. A generic competitor cannot just replicate that facility overnight. On top of that, Tyvaso DPI has orphan drug status, and any generic company trying to copy it would face an uphill regulatory battle to prove bioequivalence and match their proprietary inhaler device. By buying scPharmaceuticals, they also locked up the technical rights and patient protocols for their under-the-skin heart failure treatment, making it very unlikely that cardiology clinics will switch to a rival product once they integrate Furoscix into their daily operations.
THE BULL CASE
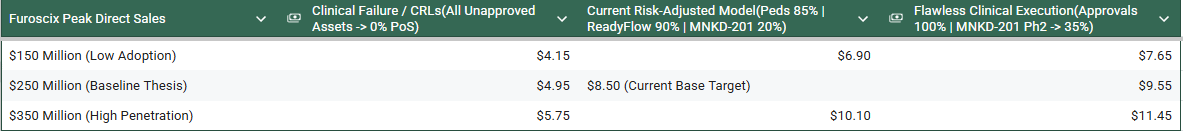
My bull case is pretty straightforward: several near-term events happen at once and force Wall Street to fix the valuation. First, the FDA approves the pediatric use for Afrezza, opening up a large market of young patients who want to avoid daily needles. Right after that, the FDA clears the Furoscix ReadyFlow device, sparking fast adoption in emergency rooms and clinics because it delivers the drug in under 10 seconds, blowing past current revenue estimates. While their own products take off, United Therapeutics continues to scale Tyvaso DPI in the lung market, sending massive, high-margin royalty checks back to MannKind. Finally, their upcoming Phase 1b data for Nintedanib DPI confirms its superior safety profile, proving it is a multi-billion-dollar asset. Once investors realize those risks are gone and that this is a highly profitable rare-disease company rather than a struggling diabetes play, the market will swap out its legacy valuation metrics for premium rare-disease multiples, easily driving the stock toward the unadjusted blue-sky range of $10.00 to $12.00. A quick caveat on the $10-12 range: While my baseline, risk-adjusted target price sits at $8.50, a flawless execution of this bull case would completely remove the clinical and regulatory haircuts currently dragging down the model. For instance, getting past these regulatory hurdles changes our unapproved asset probabilities from 85% and 20% up to 100%, automatically removing the risk-discount from future cash flows.
THE BEAR CASE
My bear case looks at what happens if their operational or regulatory plans hit a wall. The biggest risk is a surprise rejection letter or heavy warning labels from the FDA for either the pediatric insulin or the new ReadyFlow device, which would completely stall their revenue growth and hurt management’s credibility. There is also a risk that integrating their recent acquisition costs far more than expected, causing marketing and administrative expenses to balloon before Furoscix sales can catch up. Competitively, if a rival launches a simpler oral or under-the-skin drug for fluid retention, or if Tyvaso DPI sales slow down due to new competition in the pulmonary hypertension space, MannKind’s royalty stream will take a major hit. If these commercial risks hit at the same time their clinical trials show unexpected lung irritation, their pipeline value drops significantly. That would burn through their cash, force a dilutive capital raise, and drop the stock down to the $1.50 to $2.00 range.
FINANCIAL POSITION, UNIT ECONOMICS, AND RUNWAY
Looking at the financial statements, MannKind is growing fast but spending heavily to support its new product launches. Total revenue for 2025 came in at $349 million, a 22% jump year-over-year, and the first quarter of 2026 kept up the pace at $90.2 million. This growth is well-distributed, driven by $128 million in annual royalties, collaboration fees, and standard insulin sales. Looking at the latest quarter, Furoscix brought in $15.5 million and Afrezza did $15.3 million. They did report a net loss of $15.9 million late last year, but that is because they intentionally increased spending on R&D and built out their sales teams for the new launches. As of March 31, 2026, they have $134 million in cash and short-term investments, and they completely wiped out their remaining $36.3 million in debt using mostly cash. Because their current products bring in steady money, I estimate they have over two full years of runway, meaning they do not need to dilute shareholders with an emergency raise. This strong balance sheet is crucial because it lets them fund their trials and launches independently.
MARKET AND COMPETITION
Section 1: Pulmonary Hypertension
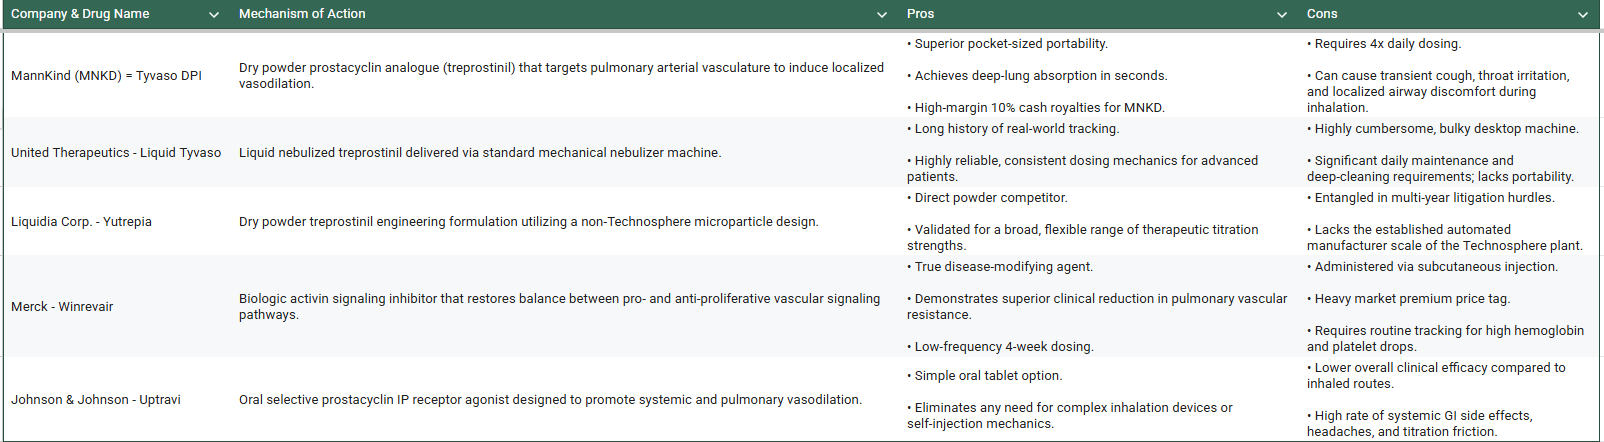
Section 2: Fluid Management & Outpatient Edema
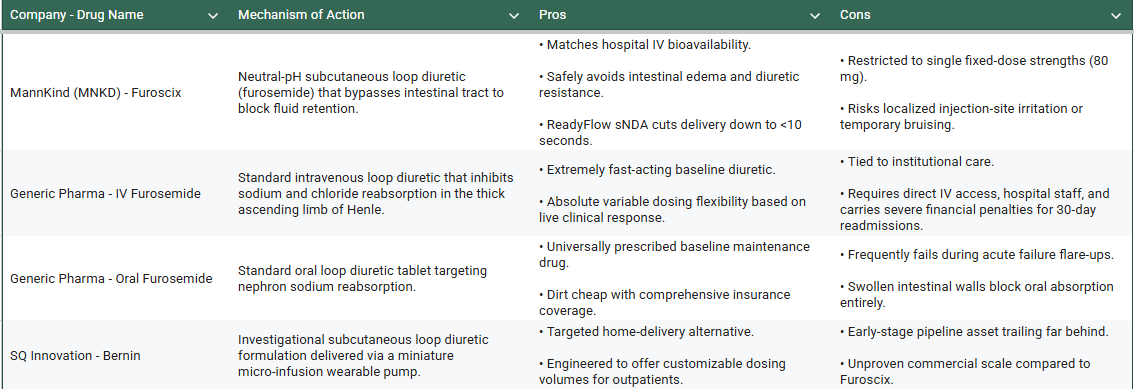
Section 3: Mealtime Glycemic Control & Rare Lung
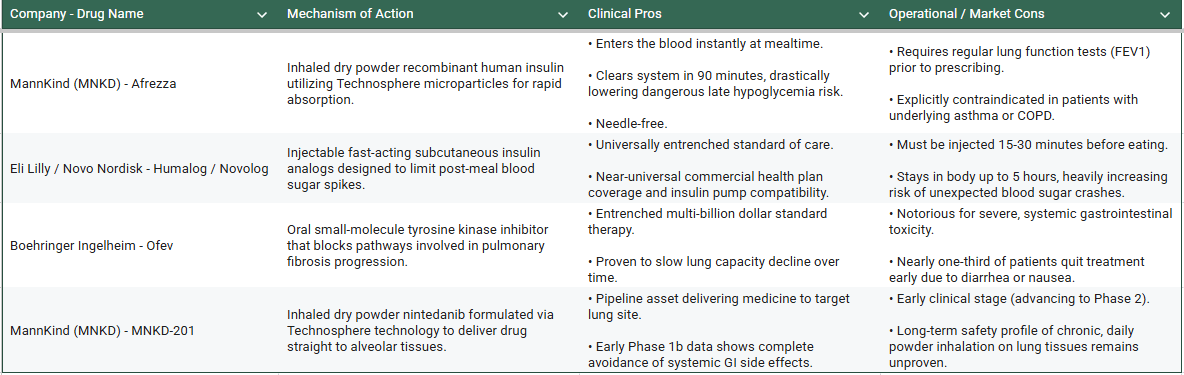
KEY CATALYSTS AND TIMELINE
FDA approval decision for Afrezza pediatric insulin use: May 29, 2026.
FDA approval decision for the Furoscix ReadyFlow Autoinjector: July 26, 2026.
First patient enrollment updates for the Phase 2 (INFLO-2) trial of inhaled Nintedanib: Q2 2026.
Early clinical data readout from the Phase 1b (INFLO-1) trial of inhaled Nintedanib: Q3 2026.
Quarterly financial reports showing sales traction for Furoscix and Tyvaso DPI: Throughout 2026.
VALUATION
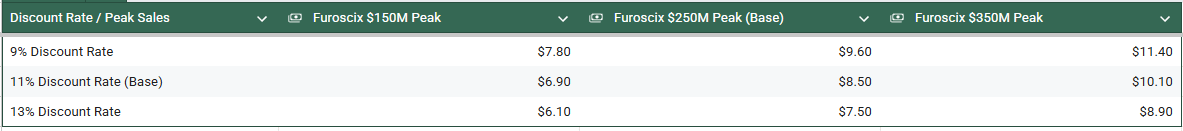
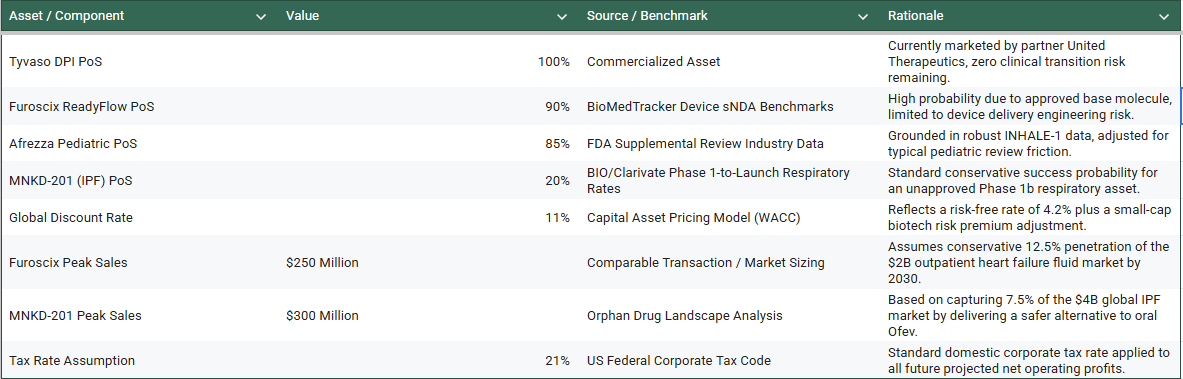
I get my target price of $8.50 by using a detailed sum-of-the-parts risk-adjusted Net Present Value model that evaluates each commercial and clinical drug through its patent life. The model uses an 11% discount rate based on a standard cost of capital calculation that includes a 4.2% risk-free rate, a 5.5% equity risk premium, a 1.4 small-cap beta adjustment, and their specific corporate borrowing costs. I use a constant 21% domestic corporate tax rate, assume everything is in US Dollars, and model cost of goods sold at 25% of revenues for their products, while mapping out their actual clinical and sales expenses over time. The risk-adjusted calculation functions by taking each year’s projected net cash flow, multiplying it by the cumulative PoS for that drug at that specific time, and discounting it back using the compound 11% rate.
Tyvaso DPI ($900 Million Peak Partner Sales)
It is important to note that $900 million is the peak partner sales estimate—meaning gross revenue for United Therapeutics, not MannKind’s direct revenue. MannKind gets a flat 10% royalty on this, translating to roughly $90 million a year in pure, high-margin cash flowing straight to the bottom line.
I set the PoS at 100% because the product is already launched. The $900 million figure acts as a conservative anchor for the model based on market dynamics. Tyvaso as a whole brand (including the old nebulized liquid version) has already cleared $1.3 billion in annual sales. Patients are aggressively switching over to the DPI version because inhaling a dry powder from a pocket-sized device is infinitely easier than hooking up to a loud liquid nebulizer machine multiple times a day. Furthermore, United Therapeutics is currently running massive Phase 3 clinical trials (the TETON studies) aimed at expanding Tyvaso into Idiopathic Pulmonary Fibrosis (IPF). By combining the ongoing format switch with an expansion into the multi-billion-dollar IPF market, United Therapeutics’ gross sales for the DPI format alone are easily modeled to top out around $900 million by the late 2020s.
Furoscix ($250 Million Peak Direct Sales)
Unlike Tyvaso, the $250 million peak sales figure for Furoscix represents direct, 100% top-line commercial revenue for MannKind, since they own the drug outright. To understand how a drug doing roughly $15.5 million a quarter right now gets to $250 million, you have to look at the massive gap in how heart failure is treated. When chronic heart failure patients experience “fluid overload,” their bodies retain dangerous amounts of water and their guts get too swollen to absorb oral water pills. Historically, the only fix was going to the Emergency Room to get pumped with an intravenous (IV) loop diuretic, landing patients in a hospital bed for days.
Furoscix is an under-the-skin injection that delivers the exact same fluid-clearing power as a hospital IV, but it can be done at home. There are over 1 million hospitalizations for acute heart failure in the US every year, making the total addressable market for avoiding these hospital stays comfortably over $2 billion. MannKind’s massive upcoming catalyst is the FDA decision on the ReadyFlow Autoinjector. If approved, it lets a patient inject that exact same dose by themselves in under 10 seconds instead of using a slow, hours-long wearable patch. This makes the drug incredibly attractive to cardiologists and emergency room doctors. To hit $250 million by 2030, Furoscix only needs to capture a modest 12.5% of that $2 billion outpatient market. I apply a combined PoS of 90% , reflecting a standard industry benchmark for a commercialized drug undergoing a device line extension.
Remaining Pipeline Components
For Afrezza, including the pending pediatric expansion, my model assumes a 95% PoS for the adult baseline and an 85% PoS for the pediatric indication based on standard FDA supplemental review success rates for validated molecules, with combined peak sales modeled conservatively at $150 million. For the internal pipeline, I model Nintedanib DPI (MNKD-201) with a 20% cumulative PoS, which represents a standard industry transition benchmark from Phase 1b to Phase 2 and eventually to market for an orphan respiratory indication, derived from BIO industry success rate benchmarks, assuming a conservative peak market penetration of 7.5% of the idiopathic pulmonary fibrosis market yielding peak sales of $300 million by 2033. To protect the numbers, I do not assume any terminal value past patent expiration, and I model a sharp 80% drop in revenue the moment the patent cliff hits.
The math scales by applying these success probabilities directly to the timeline. For approved assets like Tyvaso DPI and adult insulin, the probability stays at 100%. For the Furoscix ReadyFlow and pediatric insulin, the probability drops to 90% and 85% respectively for the new revenues starting later this year. For Nintedanib DPI, the probability is locked at 20% right now based on its early clinical stage, but as soon as it clears the Phase 2 trial, that number steps up to 35% based on industry benchmarks, which is a massive valuation catalyst for the stock. Adding up the present values of all these risk-adjusted pieces gives the company an aggregate equity value of roughly $2.6 billion. When you divide that by their fully diluted share count of 305 million shares, it gives you a fair value of $8.50 per share. The main drivers that could skew this model are changes to the discount rate and how much market share Furoscix actually grabs.
Discount Rate Sensitivity Table
PoS Sensitivity Table
Assumption Sources
Disclosure
This Due Diligence report is for informational purposes only and does not constitute financial advice or a recommendation to buy, sell, or hold any securities. The information is based on public filings and media reports and may not be exhaustive or entirely accurate. Investing in biotechnology companies, especially those in clinical stages of development, involves inherent risks, including the complete loss of capital. Clinical trial outcomes, regulatory pathways, and eventual commercial success are subject to uncertainty. Readers should conduct their own thorough due diligence and consult with a qualified financial advisor before making any investment decisions. The author may hold long/short positions in Mannkind Corporation ($MNKD) and has received no compensation for this report.